
Talk With Experts: +91 9110017086
A CIBIL score of 580 can feel like a closed door. Loan applications get rejected, credit cards are hard to come by, and even if offers do appear, they come with exorbitant interest rates. This score reflects your past financial behavior—and behavior can change. In this blog, we will outline a practical plan to improve your credit score and explain how the credit-building service from Credrinmukt which is a debt settlement company in India —can save you from months of hard work and costly mistakes.
Why Your CIBIL Score Dropped
Find the cause before you fix anything. Different damage needs a different repair.
Common Reasons for a Low Score
-
- Missed or delayed EMIs on personal loans and credit cards
-
- Card utilisation above 50 to 60 percent of your limit
-
- Loans marked “Settled” or “Written Off”
-
- Too many loan applications in a short window
-
- Errors such as a closed loan still showing as active
How a Loan Settlement Affects Your Score
Settling a loan for less than the full amount stops recovery calls, but the lender reports it as “Settled” instead of “Closed”. Lenders read this as partial repayment. The remark stays visible for years, so your plan must include repairing the damage, not just ending the debt.
How to Improve Your CIBIL Score
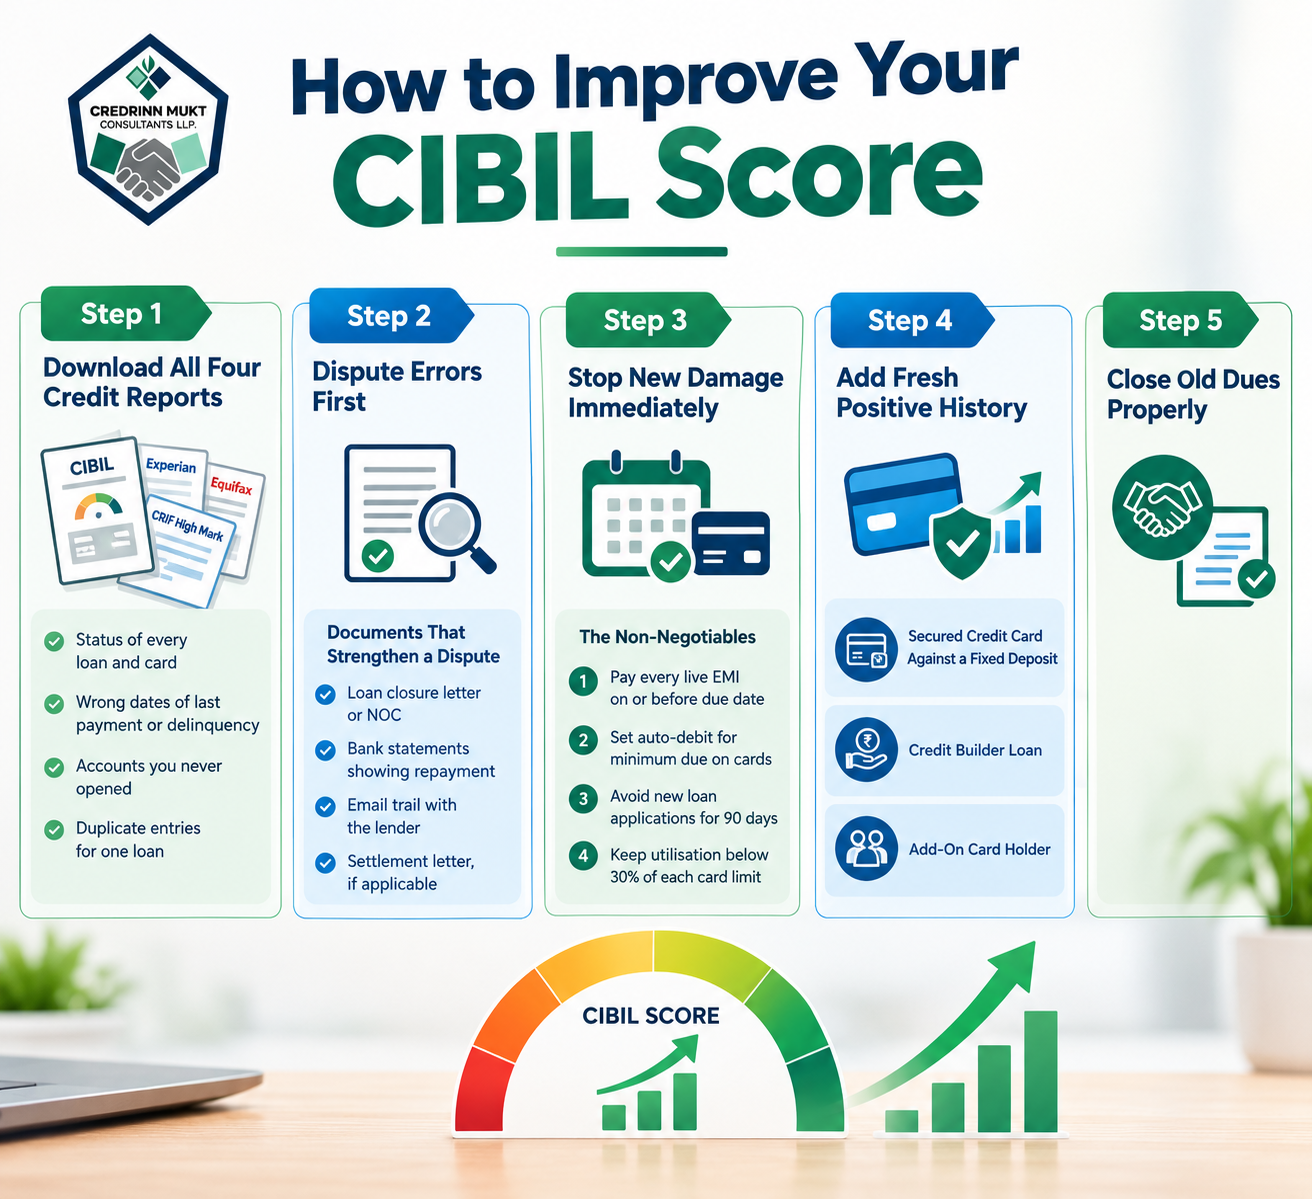 Step 1: Download All Four Credit Reports
India has four credit bureaus: CIBIL, Experian, Equifax and CRIF High Mark. Each must give you one free full report every year. Pull all four, because lenders may check any of them.
What to Look For
-
- Status of every loan and card
-
- Wrong dates of last payment or delinquency
-
- Accounts you never opened
-
- Duplicate entries for one loan
Step 2: Dispute Errors First
This is the fastest win when you improve your CIBIL score. Raise a dispute on the bureau’s portal with proof. The bureau sends it to the lender, who must respond within the regulatory timeline. A corrected entry can lift your score without costing you anything.
Documents That Strengthen a Dispute
-
- Loan closure letter or NOC
-
- Bank statements showing repayment
-
- Email trail with the lender
-
- Settlement letter, if applicable
Step 3: Stop New Damage Immediately
Rebuilding fails when fresh defaults land on top of old ones.
The Non-Negotiables
-
- Pay every live EMI on or before the due date
-
- Set auto-debit for at least the minimum due on cards
-
- Avoid new loan applications for 90 days
-
- Keep utilisation below 30 percent of each card limit
Payment history carries the most weight in score calculation, so six clean months matter more than any shortcut.
Step 4: Add Fresh Positive History
When mainstream lenders say no, these products are made for people in your position.
Secured Credit Card Against a Fixed Deposit
Open an FD and get a card against it. The limit is backed by your deposit, so approval is easy. Use it for small monthly bills and repay in full.
Credit Builder Loan
A small loan with a short tenure and a clean repayment record gives bureaus new positive data. Pick an amount whose EMI never strains your budget.
Add-On Card Holder
Being added to a family member’s well-managed card can help you build a track record. Their habits affect the account, so choose someone disciplined.
Step 5: Close Old Dues Properly
Open unsecured debts make rebuilding nearly impossible, because every unpaid month adds new negative marks. Negotiating and closing the account is often the turning point. After settlement, ask the lender in writing to update the status and get a closure letter. For structured help.
How does CredRinn Mukt’s Credit Score Builder Service help you?
Instead of generic advice, CredRinn Mukt’s Credit Score Builder Service provides a personalized plan and assigns a dedicated person to work with you and monitor your progress.
What can you expect?
-
- A review of reports from all four bureaus, with every negative entry marked
-
- Preparation of dispute applications backed by appropriate evidence
-
- Creation of a payment calendar aligned with your income schedule
-
- Guidance on utilization limits and the timing of credit inquiries
-
- Assistance in transitioning from settled or overdue accounts to a clean credit profile
Who benefits the most?
-
- Individuals whose CIBIL score has dropped below 650 due to missed payments
-
- Borrowers who have recently completed a loan settlement
-
- Anyone whose application for a home loan, car loan, or credit card has been rejected in the last six months
-
- Self-employed applicants with a limited or poor credit history
At CredRinn Mukt, you get help managing debt alongside improving your credit score; this ensures a single team understands your entire financial situation—from past dues to new financial habits
A Realistic 90-Day Credit Score Rebuild Plan
Days 1 to 15: Audit and Dispute
Collect all four reports, list every error and file disputes with proof.
Days 16 to 45: Stabilise
Clear small overdue amounts, set auto-debits and bring card utilisation under 30 percent.
Days 46 to 90: Build New History
Use one secured card or builder loan and repay on time every cycle. Re-check your reports at day 90.
Expect gradual movement. Bureaus update monthly, and entries such as defaults and settlements stay on file for several years, so the goal is a steady rise backed by new positive data.
Conclusion
To rebuild your credit score, understand the damage, fix the errors, stop new defaults and add fresh positive history. Do this consistently and your CIBIL score recovers. If the process feels heavy, a trusted credit score builder service can shorten the learning curve. Call CredRinn Mukt at 9110017086 or use our contact page to get a clear plan built around your reports.
Frequently Asked Questions
1. How can I improve my CIBIL score after missing EMIs?
Clear overdue amounts, pay every EMI on time, keep card utilisation under 30 percent and dispute any wrong entries. Consistent on-time payments for several months lift the score steadily.
2. How long does a credit score rebuild take?
Most people see visible improvement in three to six months. Reaching 750 or above after a default or settlement often takes 12 to 24 months.
3. Can I rebuild my credit score after loan settlement?
Yes. The “Settled” remark stays on the report, but new on-time payments, low utilisation and a healthy credit mix reduce its impact on future lenders.
4. What is a credit score builder service?
It is a guided service that reviews your credit reports, helps correct errors, plans repayments and advises on products that add positive history.
5. Can a CIBIL score improve in 30 days?
Small gains are possible if you fix report errors, clear overdue amounts and cut card utilisation. A large jump in one month is unrealistic.
You May also like – Credit Card Debt Settlement: How It Works, Eligibility, Process & CIBIL Impac